How to Calculate the Total Cost of Borrowing a Personal Loan in Arizona
MW
Margaret Wack
Personal Finance Writer · Updated October 2026
Margaret Wack
Personal Finance Writer · Updated October 2026
Imagine you are sitting at your kitchen table in Mesa, looking at a $15,000 estimate for some much-needed home renovations. You find a loan offer with a monthly payment that looks perfectly manageable. However, many borrowers in Arizona make the mistake of only looking at that monthly number without considering the long-term implications. In 2026, as economic conditions continue to shift, understanding the true cost of your debt is more critical than ever before. You might find that what seemed like a bargain actually costs you thousands more than anticipated once all the math is settled.
To truly understand if a loan fits your budget, you must look beyond the principal amount and the sticker price interest rate. For instance, in 2026, personal loan APRs for borrowers with excellent credit may range from 6% to 12%, while those with lower credit scores could see rates climbing as high as 34% or more. Furthermore, the term of your loan—whether it is 24 months or 72 months—can drastically alter the total amount you pay back to a lender. A single decision to extend your timeline by just one year can result in an extra several thousand dollars in interest payments.
This article is designed to give you the tools and mathematical frameworks needed to master your own debt calculations. We will walk through how to differentiate between simple interest and APR, how to account for hidden fees, and how to run your own comparisons using real-world numbers. By the time you finish reading, you will be equipped to look at any loan offer from an Arizona lender and know exactly what it will cost you from the first day of borrowing until the very last payment is made.
One of the most significant points of confusion for borrowers in 2026 is the distinction between the 'interest rate' and the Annual Percentage Rate (APR). While they sound nearly identical, they represent very different figures when it comes to your wallet. The interest rate is the cost you pay each year to borrow the principal amount. However, the APR is a more comprehensive number that includes both the interest rate and any additional fees required to close the loan, such as origination fees or processing costs.
For example, if you are looking at a loan in Phoenix with an interest rate of 10% but there is a 3% origination fee tacked on at the start, your APR will be higher than 10%. This is because the lender is essentially charging you for the service of providing the money upfront. Always prioritize the APR when comparing two different loan offers, as it provides a more honest view of the total annual cost of borrowing.
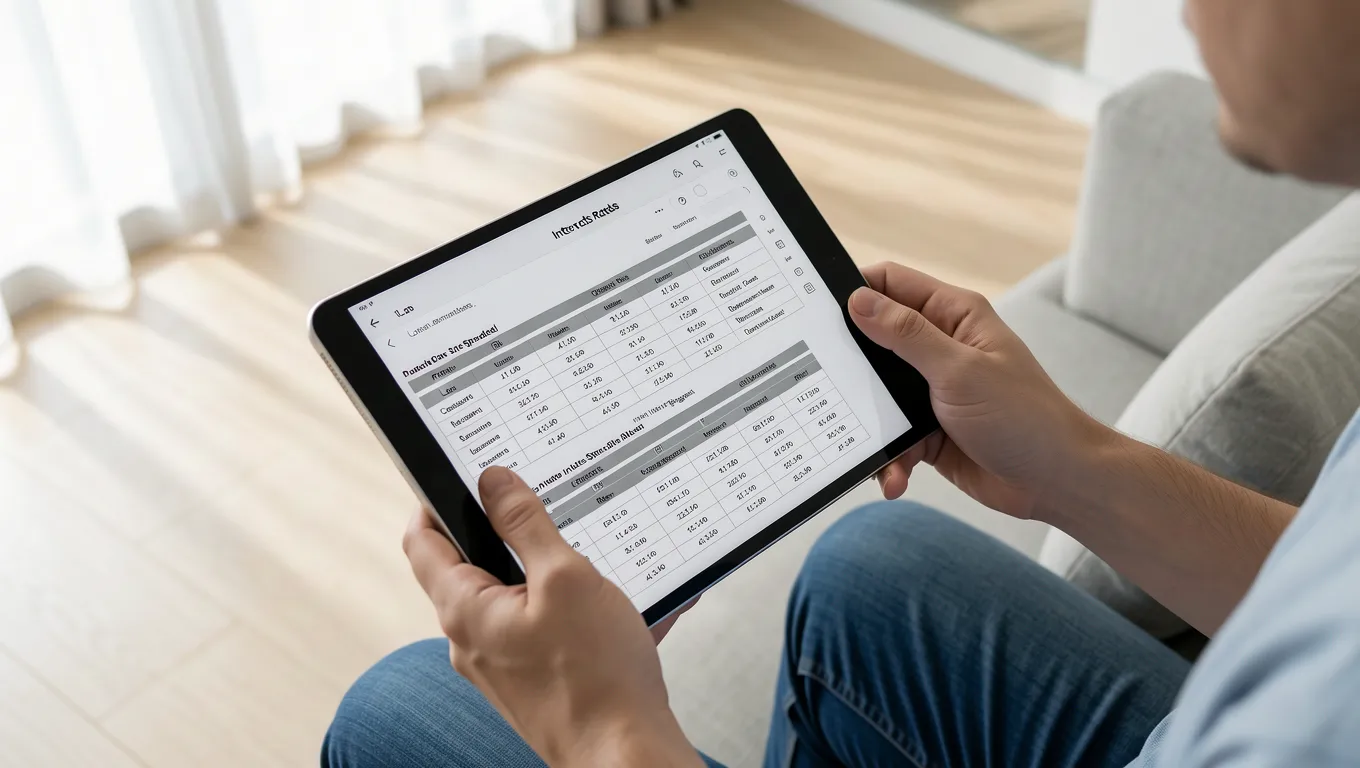
To understand this in practice, consider these components that make up your APR:
Calculating the true cost of a loan does not require a degree in finance, but it does require a systematic approach. If you want to move beyond guesswork and gain absolute certainty about your financial obligations in 2026, follow this four-step decision framework:
Step 1: Identify the Total Principal and Fees. Do not just look at the amount being deposited into your bank account. Look for the total amount you are responsible for repaying. If you borrow $10,000 but a fee of $500 is taken out immediately, your actual debt is still $10,000, but your effective cost has just increased.
Step 2: Determine the Monthly Payment. Most lenders will provide this number, but it is wise to verify it using an amortization calculator or a simple spreadsheet. If you cannot find this number clearly, ask the lender directly for a breakdown of what each monthly payment covers.
Step 3: Multiply the Payment by the Term Length. This is the simplest way to see your total repayment amount. If you have a $400 monthly payment and a term of 48 months, your total outflow will be $19,200 ($400 x 48).
Step 4: Subtract the Original Principal. By taking your total outflow (from Step 3) and subtracting the original loan amount, you arrive at the total interest cost of the loan. This number is what you are truly paying for the privilege of using the lender's money.
It is incredibly tempting to choose the loan that offers the smallest possible monthly payment. In a high-inflation environment like what we might experience in 2026, keeping more cash in your pocket every month feels like a win. However, this strategy often carries a hidden trap: extended repayment terms.
Let us look at an honest comparison between two different strategies for a $15,000 loan to see how this plays out in real numbers.
Option A: You choose a shorter-term loan with higher monthly payments. Let's say you take 36 months at a 9% APR. Your monthly payment would be approximately $473, and your total cost over the life of the loan would be roughly $17,028.
Option B: You choose a longer-term loan to ease your monthly budget. You take 60 months at an 11% APR. Your monthly payment drops significantly to about $329, but your total cost over the life of the loan jumps to approximately $19,740.
By choosing Option B just to save $144 per month in the short term, you end up paying an extra $2,712 in interest. This is a classic trade-off: you are essentially buying 'monthly breathing room' at the expense of your long-term net worth.
Even with a perfect calculation of interest rates, there are two 'silent killers' in personal lending that can derail your financial plan. The first is the origination fee, which we touched on earlier. In 2026, many lenders continue to use these as a primary way to generate revenue without raising their advertised interest rates.
The second, and perhaps more dangerous, factor is the prepayment penalty. Many borrowers believe that if they get a bonus at work or a tax refund, they can simply pay off their loan early to save on interest. However, you must check your contract for prepayment penalties before signing. Some lenders include clauses that charge you a fee if you pay the loan back too quickly because it prevents them from collecting all the interest they expected to earn.
To avoid these pitfalls, follow this checklist when reviewing an offer:
To make this concept even more concrete, let's walk through three distinct scenarios that a resident of Scottsdale or Tucson might encounter when seeking funds for various needs.
Scenario 1: The Emergency Car Repair. A borrower needs $5,000 to replace an engine. They secure a loan at 12% APR with a 24-month term. Their monthly payment is $237.65, and the total cost of borrowing is $5,703.60. This is a relatively low-cost way to handle an emergency.
Scenario 2: The Home Improvement Project. A homeowner wants to landscape their backyard for $12,000. They find a deal at 15% APR with a 48-month term. Their monthly payment is $336.95, and the total cost of borrowing is $16,173.60. Here, the interest adds nearly $4,200 to the project's price tag.
Scenario 3: Debt Consolidation. A borrower takes a large $25,000 loan at 18% APR with a 72-month term to consolidate high-interest credit cards. Their monthly payment is $541.65, and the total cost of borrowing is $39,000 (rounded). In this case, they are paying $14,000 in interest alone. While it may simplify their life by consolidating multiple payments, the long-term cost is substantial.
As we move through 2026, the Arizona financial landscape continues to be shaped by broader economic trends. The Federal Reserve's decisions on interest rates have a direct impact on how much lenders can charge for personal loans. When the Fed maintains high rates to combat inflation, your options for low-interest borrowing may become more limited.
For residents in growing areas like Gilbert or Chandler, the cost of living and housing is constantly evolving. This makes it vital to be a disciplined borrower. Before you commit to any loan, remember that Arizona Zip Loan is just one resource among many that can help connect you with potential lenders; it is not a lender itself. You should always compare offers from local credit unions, national banks, and online lenders.
Ultimately, the best way to navigate this landscape is through preparation. The more work you do on your math before you ever step into an office or click 'apply' online, the better prepared you will be for whatever economic climate 2026 brings. Knowledge of your total cost is your greatest defense against unnecessary debt.